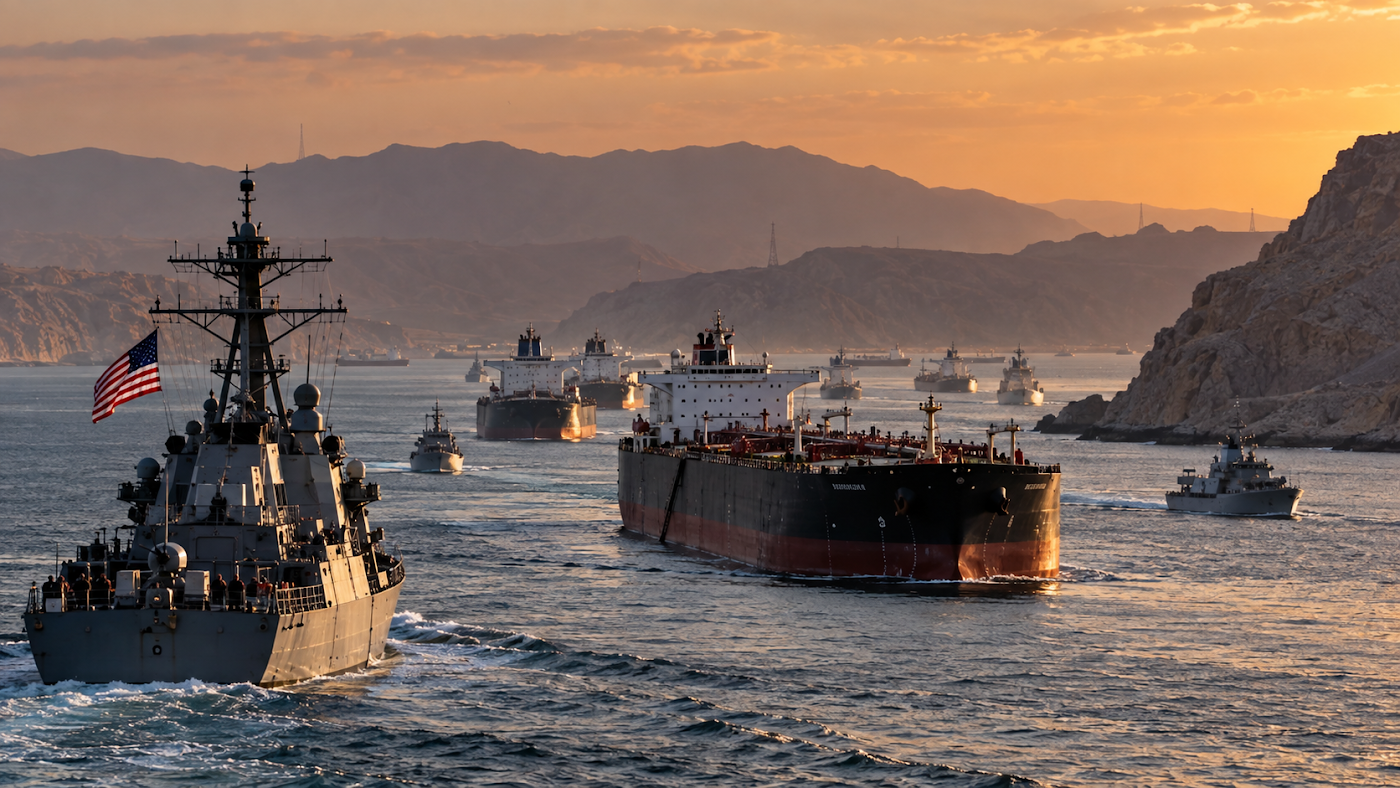
Wall Street ended Friday deciding that weak does not mean broken.September payrolls rose just 61,000, well below the 90,000 forecast, while unemployment climbed to 4.4%. Stocks treated the miss as room for the Fed to ease rather than a recession signal. The S&P 500 closed near 7,700 and the Dow ended near 51,170. All three rose modestly and recovered much of the week’s earlier yield-driven losses. The 10-year Treasury yield, which touched a 24-year high during the week, fell back toward 4.62% as traders increased bets on an October 28 cut. Futures point slightly higher Monday. S&P 500 futures gained about 0.2%, while Nasdaq-100 futures rose 0.3%. Japan’s Nikkei added 0.4%, while Hong Kong slipped as U.S.-China chip tensions returned. Three Fed speakers arrive before Friday. September CPI lands Thursday. The Signal Payrolls gave the Fed room to ease without convincing markets that growth is breaking. CPI now decides whether that room survives. Premier Feature Carnegie didn't invent steel. He used new technology to produce it cheaper and faster than anyone on Earth. Rockefeller didn't discover oil. He used industrial machinery to refine it more efficiently. Vanderbilt didn't build the railroad. He understood that whoever controlled the infrastructure controlled the economy. Their combined fortunes were between $700 billion and $1 trillion. Best-selling financial author Alexander Green has identified three companies positioned to be the Titans of the AI age. CLICK HERE TO FIND OUT WHO THEY BEFORE THE WINDOW CLOSES Brent gained, not eased, and the reason is on the water, not in a diplomatic cable.Iran confirmed last week that it received the U.S. response to its seven-day plan for reopening the Strait of Hormuz. The message came through Qatari mediators, but no formal Iranian response had emerged by Sunday night. Brent is up $3.07 on the day to $102.55, after at least four commercial vessels came under missile and drone attack transiting Hormuz since Friday. One tanker caught fire in its engine room inside the strait Sunday; another sustained port-side damage roughly four nautical miles east of Oman. UKMTO logged all four incidents over the weekend, and ING Bank's desk flagged a renewed uptick in attacks on commercial shipping across the Gulf. The G7 pushed back the other way. The bloc agreed to release up to 100 million barrels of emergency crude stocks over the next four months through the IEA, days after Washington issued its own request for proposals to exchange up to 40 million barrels from the SPR. Neither has slowed the barrel's climb. ING called the coordinated release itself a sign of "growing tightness," not relief. U.S. Strategic Petroleum Reserve stocks remain below 300 million barrels, their lowest level since January 1983. Shipping insurers have kept war-risk premiums elevated on Gulf routes for months; this weekend gave them no reason to reconsider. Energy Signal Diplomacy stalled. The attacks didn't. Brent above $100 is now being driven by tankers getting hit, not by what Tehran hasn't said yet. The labor market just strengthened the dovish case.Friday’s 61,000 payroll gain, combined with a weaker August revision and 4.4% unemployment, gives Fed Chair Kevin Warsh a clearer argument for easing on October 28. But one jobs report does not settle the meeting. Three Fed speakers are due this week and will give markets their first look at how officials read the slowdown. Their comments matter because the committee has not signaled a clear agreement on the next move. Then comes CPI. September inflation lands Thursday, just days before the Fed enters its quiet period. A soft print would support the message from payrolls and strengthen the cut trade. A hot number would put inflation back against weaker hiring. Macro Signal Payrolls opened the door to an October cut. CPI decides whether the Fed can walk through it. From Our Partners A "bloodbath" Is Coming
Silicon Valley billionaires are hoarding guns, gold, and even military grade gas masks... or fleeing the country altogether. What do they know that you don't? This AI insider is stepping forward with this time-critical message: Move your money before October 31st, ahead of the dangerous next phase of the AI market. Here's the one urgent move you need to make with your money immediately. This ad is sent on behalf of TradeSmith at 1125 N. Charles Street, Baltimore, Maryland 21201. If you're not interested in this opportunity, please click here. The AI buildout is moving from chips toward power and infrastructure.Oracle (ORCL) enters the week with momentum from its Tencent chip agreement and reports that it is considering more data-center capacity in Malaysia and Japan. Constellation Energy (CEG) remains supported by its 20-year nuclear power agreement with Amazon (AMZN). The deal fits a wider shift in the AI trade as electricity supply becomes a larger limit on new data centers. Accenture (ACN) is attacking another constraint. Its AI-safety partnership with Anthropic is building teams to test frontier models before companies deploy them internally. Demand for those evaluations is rising as enterprise AI use expands. Bank earnings begin next week, adding another test. Investors will watch net interest margins for signs that lenders are preparing for a faster Fed easing cycle. Capital Signal The AI trade is no longer just about finding enough chips. The next limits are power, data-center capacity and safe deployment. Bitcoin held its ground over the weekend while the marginal dollar moved elsewhere.BTC traded near $86,000, up from roughly $85,400 Thursday. But XRP and Solana ETFs attracted fresh money while Bitcoin funds showed less direction. That rotation has a longer history. DWF Labs estimates spot Bitcoin ETFs lost about $5.4 billion during the first half of 2026, their first negative half-year since launch. Roughly $80 billion remains in the category, but newer crypto products are competing harder for fresh institutional capital. Bitcoin increasingly looks like the mature allocation while investors use smaller products for higher-beta exposure. Policy is moving too. The Senate Banking Committee advanced work on crypto tax rules tied to stablecoin transactions. At the same time, the OCC is reviewing new national trust charter applications from payments companies seeking direct custody rights. That fight matters because it decides which firms can hold stablecoin reserves without relying on traditional bank partners. CME crypto futures open interest also increased into the weekend. Institutional desks appear to be positioning for volatility around Thursday’s CPI report rather than reducing exposure before it. The Verdict Bitcoin is holding near $86,000. The more important move is happening around it. XRP and Solana are competing for new ETF money. Stablecoin tax rules are moving through Washington. Payments firms are pushing for direct custody rights. Bitcoin built the institutional market. It no longer owns every new institutional dollar entering it. Partner Spotlight Middle East Conflict Lights Fuse on US Debt BombAmerica was already drowning in $38 trillion of debt, but the recent conflict in the Middle East just accelerated the timeline. As oil spikes, a 100-year-old stock market signal that accurately predicted the 2008 and 2020 crashes is flashing a massive "Sell" on dozens of popular U.S. equities. If you hold the wrong stocks when this debt crisis hits, it could wipe out years of gains. Click here to see the 10 popular stocks to dump immediately 11780 US Highway 1, Palm Beach Gardens, FL 33408-3080 Would you like to edit your e-mail notification preferences or unsubscribe from our mailing list? Copyright © 2026 Weiss Ratings. All rights reserved. Monday starts with markets leaning dovish, but the case is not complete.Payrolls added just 61,000 jobs and unemployment reached 4.4%. That gave the Fed room to consider an October cut. Now CPI has to confirm it. AI spending is moving from chips toward power, infrastructure and safety. Bitcoin is holding near $86,000 while altcoin ETFs compete for fresh capital. Thursday is the hinge. A soft CPI print would reinforce Friday’s labor signal and strengthen the October cut case. A hot print would put the Fed back between weak hiring and stubborn inflation, three weeks before it has to choose. 3 Stocks at a Major Turning PointSomething unusual is happening beneath the surface of three widely followed stocks.
In each case, the fundamentals are saying one thing... while institutional activity, management signals or the options market are saying something else. That kind of disagreement can matter. Because when the evidence stops lining up, the next move in the story often comes down to a handful of signals most investors never think to watch. Our new FREE Market Tell Special Report breaks down three of these situations, and shows you exactly what we’re watching next. Get the Free Report: 3 Stocks at a Major Turning Point → |
|