Brent climbed above $106 after Trump rejected Iran’s Hormuz proposal, while the 10-year hit 5.21%. Bitcoin slipped toward $84,000 despite $2.4 billion of weekly ETF inflows as markets turn to PCE Wednesday and payrolls Friday.
MARKET PULSE

The weekend changed the tape.

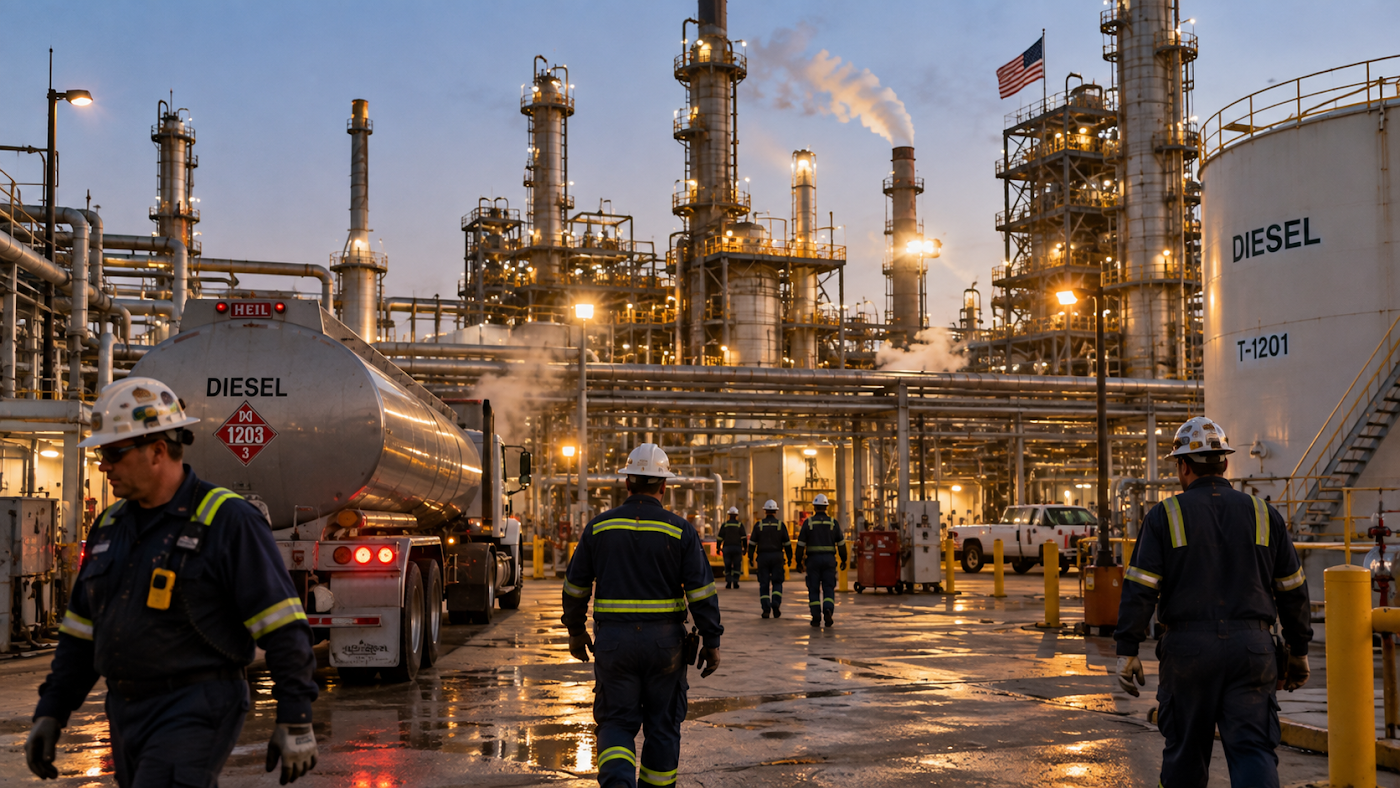
S&P 500 futures fell about 0.4% Monday morning, with Nasdaq futures down a similar amount after President Trump rejected Iran’s proposal to reopen the Strait of Hormuz. Brent moved back above $106.

Friday had ended on a different note. The S&P 500 gained 1.2% for the week, while the Nasdaq rose 2.1%, their best weekly performances since early August.

Asia felt the reversal. Japan’s Nikkei 225 fell 0.12%, while South Korea’s Kospi dropped 2.36% as higher energy costs returned as a concern for manufacturers. Hong Kong’s Hang Seng gained 0.76%.

This week brings the data that can reset the rate trade. JOLTS lands Tuesday. PCE and Micron (MU) arrive Wednesday. ISM Manufacturing follows Thursday, with September payrolls Friday.

The 10-year Treasury yield is already near 5.21%, its highest since 2007.

The Signal

The diplomatic relief trade ended over the weekend. Oil is above $106 and yields are above 5.2%. This week’s data now decides whether October brings another hike.

Premier Feature

AI's "All In" Moment

In the dot-com days, former Wall Street money manager Alexander Green bought Apple under $1. Netflix at $1.62. Amazon under $2. (Split adjusted.)

Now he's doing the same with AI.

And he says it's the biggest opportunity he's seen in 40 years.

Every few decades, a window opens that can change your financial life forever.

CLICK HERE TO GET THE FULL STORY BEFORE IT'S TOO LATE

ENERGY

Trump reset the Hormuz timeline.

Brent rose above $106.14 Monday, while WTI climbed toward $93.55 after Trump rejected Iran’s latest proposal.

Iran wants Washington to end its naval blockade before full shipping access returns. The U.S. has rejected those terms, leaving the two sides stuck around the same issue that broke earlier talks.

The physical market remains constrained.

JPMorgan(JPM) estimates Middle East oil flows near 17 million barrels per day, more than 70% of the 2025 average but still well below normal levels.

Oman is trying to broker another framework after the June agreement collapsed and tanker attacks resumed. A path toward a deal exists. The terms still do not.

Energy Signal

Trump’s rejection put Brent back above $106. That makes Hormuz more than a geopolitical risk this week. Oil feeds directly into inflation expectations as PCE approaches.

MACRO

The most important week for rates starts with the 10-year at 5.21%.

The Fed raised rates by 25 basis points this month to a range of 3.75% to 4.00%. Markets now price three more hikes by mid-2027.

This week will test that path.

JOLTS arrives Tuesday. Wednesday brings ADP employment, August PCE and the third estimate of Q2 GDP. ISM Manufacturing follows Thursday before September payrolls Friday.

The Cleveland Fed’s nowcast has headline PCE running near 3.78% year over year, with core PCE around 3.40%. Both remain well above the Fed’s 2% target.

Futures markets ended last week pricing the fed funds rate near 4.2% by December.

A hot PCE report makes another October move easier to justify. Softer inflation and weaker payrolls would give the Fed its first real case for a pause.

Macro Signal

PCE Wednesday and payrolls Friday decide whether October 27 remains a live hike. Both arrive with yields already at 19-year highs.

From Our Partners

Louis Navellier: My #1 AI stock for 2026 (name & ticker inside)

"I want to give you a free stock pick today. This company's sales are up 28% year over year. It holds over 30,000 patents in wireless and video technology. And it just earned an A-rating in my proprietary Stock Grader system. That's the same system that helped me flag Nvidia back in 2005 — before its 82,000% run. In fact, this system has identified the top-performing S&P 500 stock for 12 years running. Over the years, it has cost me $9 million to build and maintain. And right now, it's flashing its highest possible rating on this AI play." — Louis Navellier Click here to see which AI stock my $9 million system is flagging right now, free.

This ad is sent on behalf of InvestorPlace Media at 1125 N. Charles Street, Baltimore, Maryland 21201. If you're not interested in this opportunity, please click here.

CAPITAL

The weekend’s biggest AI story happened away from the market.

Trump hosted Anthropic CEO Dario Amodei for a private dinner Sunday, their first one-on-one meeting.

The meeting follows months of tension involving the Pentagon, export controls and a legal fight over the use of AI in autonomous weapons. Those disputes remain unresolved.

The timing matters.

Trump and House Speaker Mike Johnson are set to meet AI executives Tuesday at the White House. Amodei’s private meeting puts Anthropic back into the policy discussion ahead of that event.

The market gets a harder AI test Wednesday when Micron reports. It will be the first major semiconductor earnings report since the Fed hike and a direct test of AI memory demand with the 10-year above 5.2%.

Capital Signal

The Amodei meeting signals a change in tone around Anthropic. Micron provides the harder test: whether AI demand can keep supporting spending as capital becomes more expensive.

CRYPTO PULSE

Bitcoin enters the week with stronger flows but a tougher macro setup.

BTC traded near $84,000 Monday after reaching above $87,000 last week. It remains more than 33% above its August low below $63,000.

ETF demand has changed sharply.

U.S. spot Bitcoin ETFs attracted about $2.4 billion last week, their strongest weekly inflow since October 2025. That pushed 2026 net flows back into positive territory at roughly $934 million after reaching a $5.8 billion deficit in July.

The rotation also moved beyond Bitcoin.

Ninety-three of the CoinDesk 100’s constituents gained last week. Solana traded near $121 Friday, up 15.5% for the week. Solana ETFs attracted $188 million, their strongest week since launch and their 12th straight week of inflows.

Solana also enters a technical upgrade window today. Anza’s Agave 4.3 schedule lists September 28 for feature activation ahead of the broader Alpenglow upgrade.

Alpenglow aims to reduce finality from 12.8 seconds to roughly 150 milliseconds. Today is a prerequisite, not the full launch. Validator adoption remains the key signal.

One risk remains from last week. Bitget suffered a $351.6 million hack. The exchange says its $464 million protection fund covers the loss, while withdrawals remain under review.

The Verdict

Bitcoin ETFs turned positive for 2026 while Solana recorded its strongest ETF week since launch. Institutional demand is back.

The immediate threat is macro. Oil above $106 and yields above 5.2% put Wednesday’s PCE and Friday’s payrolls directly in crypto’s path.

Partner Spotlight

Buffett, Gates and Bezos Quietly Dumping Stocks—Here's Why

The world's wealthiest individuals are making huge moves with their money.

Warren Buffett just liquidated billions of shares. Bill Gates sold 500,000 shares of Microsoft. Jeff Bezos filed to sell Amazon shares worth $4.8 billion.

What is going on? One multi-millionaire believes they are preparing for a catastrophic event. But not a crash, bank run, or recession. It’s something we haven’t seen in America for more than a century.

For the full story, click here.

CLOSING LENS

Monday begins with the relief trade reversing.

Iran talks produced another proposal. Trump rejected it. Brent returned above $106.

Bitcoin still has $2.4 billion of weekly ETF inflows behind it. AI still has Micron earnings and a White House summit ahead.

But every trade meets the same constraint.

The 10-year is at 5.21%.

PCE Wednesday and payrolls Friday decide whether that pressure gets worse. Hot inflation and firm hiring keep October alive. Softer data gives the Fed a case to pause.

The market knows what it wants.

This week tells it what it gets.

3 STOCKS OUR SIGNAL ENGINE SAYS TO WATCH CAREFULLY

Three stocks. Three signals. Two weeks later, the story changed.

On September 2, we published three market questions around KLAC, HPE and PG&E.
Two weeks later, every one of them produced new evidence.

One company delivered record revenue and raised its outlook.
Another saw weakness spread across its entire peer group.
And in the third, a market risk that had only been showing up beneath the surface suddenly became explicit.
Yet none of these stories is finished.

That’s why we built Market Tell.
To track the signals that keep moving after the headline is gone — and show you what investors should be watching next.

We’ve put the latest analysis into a new FREE Special Report:
3 Stocks at a Major Turning Point

See what changed… what still hasn’t been resolved… and the signals we’re watching now.

Get the Free Report →