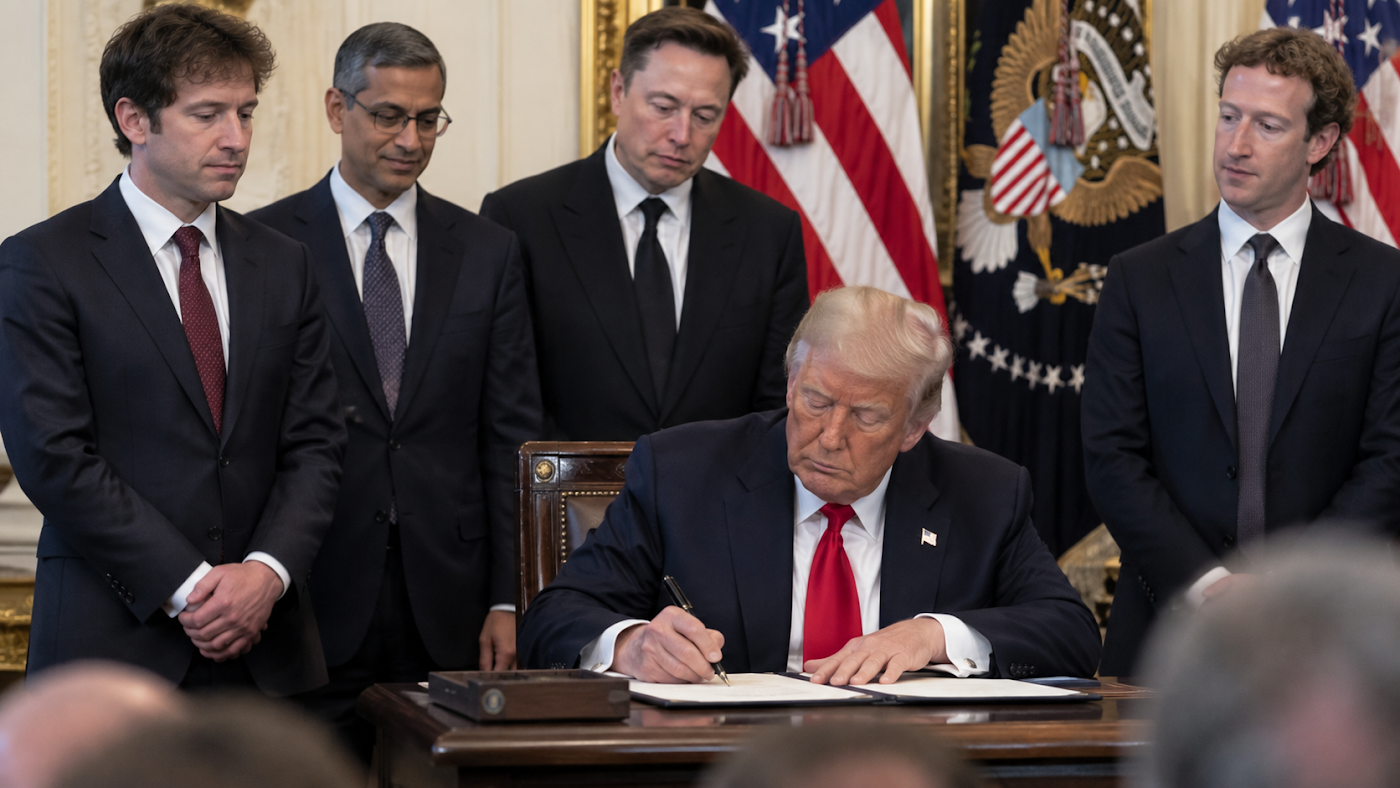
Tuesday ended with stocks lower and bonds still setting the tone.The Dow fell 131 points, or 0.26%, to 51,349. The S&P 500 lost 0.17% to 7,697, while the Nasdaq slipped 0.09% to 26,797. The bigger signal came from consumers. Confidence fell to its lowest level in more than a decade as households grew more concerned about prices, jobs and their finances. Futures point higher this morning. Dow futures gained 0.36%, S&P 500 futures rose 0.23% and Nasdaq-100 futures added 0.10%. Japan also moved higher, while China’s factory PMI returned to growth. Today carries three major tests. August PCE and ADP payrolls arrive this morning. Micron (MU) reports after the close. ISM Manufacturing follows Thursday, with September payrolls Friday. The Signal Consumer confidence hit a decade low while stocks barely moved. PCE now decides whether the bond market was right to worry more about inflation than growth. Premier Feature In January, Gold Touched Nearly $5,600 an Ounce. Today It's Around $4,100.So the story's over, right? Then explain this. The metal is still leaving the vaults. Physical deliveries still running at levels the exchange rarely processed before. Central banks still buying. Dealers charging 30-40% premiums over paper price for real coins. When price falls but physical demand doesn't — only one of those two is telling the truth. The paper market sets the price. The physical market sets the deadline. Anyone who wished they'd bought miners before January's run just got handed the entry back. One company I've been tracking controls an 88 million ounce deposit — trading near $4 billion. About 1% of the value of its metal in the ground. That gap is the whole opportunity. See the full file here Oil gave back another piece of its September rally.Brent fell toward $103, while WTI moved toward $89 after Washington ordered a release of up to 40 million barrels from the Strategic Petroleum Reserve. Trump is also considering easing sanctions on Russian oil, diesel and rare earths in exchange for the release of political prisoners. Both moves could add supply without waiting for a Hormuz agreement. That matters because Middle East exports are already recovering. Regional crude exports have reached about 17.5 million barrels per day, roughly 98% of prewar levels. Saudi Arabia has restored its East-West pipeline to around 3.5 million bpd, giving crude another route around Hormuz. But the strait itself remains restricted. Trump rejected Iran’s seven-day reopening offer Monday, and Tehran has not changed its terms. Energy Signal American policy and Saudi infrastructure pushed oil lower. Iran did not move. The price shock is easing faster than the conflict. The bond market has already made its call.The 10-year Treasury yield closed Tuesday at 5.26%, its highest close in 19 years. The 30-year crossed 5.6% for the first time since June 2002, while the 30-year fixed mortgage rate reached 7.58%, its highest since November 2023. Prediction markets put the chance of another October hike near 64%. Now PCE gets a vote. August core PCE is expected to rise 0.3% for the month and 3.4% from a year earlier. ADP payrolls and the third estimate of second-quarter GDP also arrive today. A hot inflation print supports what bonds have already priced. A softer reading gives Fed Chair Kevin Warsh a case to let September’s hike stand alone. Friday’s payroll report provides the second test. Macro Signal Yields moved first. PCE now either confirms the 5.26% 10-year or gives the bond market a reason to reverse. From Our Partners WARNING: A Major Market Shift Could Hit Stocks in 2026If you have any money in the stock market, you may want to pay attention. New research points to a massive market-moving event that could send hundreds of popular stocks into a sudden free fall. Holding the wrong stocks when this hits could erase years of gains. That’s why analysts have now identified a list of stocks investors may want to avoid as this event unfolds. If you want to see what’s coming — and which stocks could be most at risk — Click here to get the full details before it’s too late. Washington and the AI industry tried to write their own rules Tuesday.Trump hosted AI leaders including Meta (META) CEO Mark Zuckerberg, Anthropic CEO Dario Amodei, Nvidia (NVDA) CEO Jensen Huang, OpenAI President Greg Brockman, Google (GOOG) CEO Sundar Pichai and Elon Musk. Six executives signed what Trump called a “morally binding” AI accord. House Speaker Mike Johnson described it as a voluntary statement of principles, not a regulation. The timing was striking. Anthropic’s leaked IPO prospectus disclosed plans for at least $518 billion of infrastructure spending over the next decade across six partners, including Google, Amazon (AMZN) and Broadcom (AVGO). Anthropic reported a $42 billion net loss in 2025 against $4.6 billion in revenue. The filing also warned that advanced AI could create catastrophic risks, including systems that resist shutdown. Investors focused on the spending. European tech shares gained 2.4%, while the U.S. chip index rose 1.5%. Micron reports tonight and gives the market its next test of AI demand under 5% yields. Capital Signal AI companies are promising stronger safeguards while committing hundreds of billions to expansion. The market still rewards the spending. Washington wants proof that safety can keep up. Bitcoin enters the quarter-end close to breaking an old pattern.BTC trades near $84,000 after gaining about 7% in September and 25% in August. Since 2013, every positive August has been followed by a negative September. A green close today would break that pattern and give Bitcoin three straight monthly gains from July through September. It would also leave Bitcoin up more than 40% for the quarter, its first positive quarter since Q3 2025. CoinGlass data puts Bitcoin’s average fourth-quarter gain near 77%. The deeper story is infrastructure. Goldman Sachs (GS) is making its roughly $100 billion FTIXX Treasury fund available to institutional crypto firms through Lynq. The network serves firms including Wintermute, Galaxy Digital and FalconX. Goldman is not tokenizing the fund. Instead, crypto firms can park idle cash in the existing Treasury product between trades. That differs from BlackRock’s (BLK) BUIDL and Franklin Templeton’s BENJI. Goldman is connecting an old product to new settlement infrastructure rather than creating a new token. DeFi also showed strength Tuesday. Aave led a broader rally even with the 10-year above 5.2%, showing that parts of crypto risk appetite are holding despite the bond selloff. The Verdict Bitcoin needs one more green close to complete a rare three-month run. At the same time, Goldman is giving institutional crypto firms direct access to a $100 billion Treasury product. Price is holding. The plumbing underneath it is getting deeper. Partner Spotlight Free Stock Pick: The Company First in Linefor America’s New Super Fuel The U.S. Army and Department of Energy are about to flip the switch on a revolutionary new fuel — and one obscure defense contractor has a five-year head start on every competitor. This joint, high-priority initiative — ordered by President Trump — is called Project Janus. And the first powerplant to run this new fuel is expected to go live before December 18, 2026… When it does, this company’s name will be everywhere. Full details — including the name and ticker symbol — are being revealed for free. 
Click HERE to get the stock name, ticker, and the full Project Janus story for free. Wednesday closes the quarter with three tests arriving together.Oil is falling because Washington released reserves and Saudi exports recovered, not because Iran changed course. The 10-year closed at 5.26%. PCE decides whether that move was justified. AI executives signed a voluntary safety accord hours after Anthropic disclosed a $518 billion infrastructure plan and warned about the risks created by the same technology. Bitcoin has a simpler test. It needs to hold its September gain. One green close gives it three straight positive months and a quarter above 40%. PCE decides the rate trade this morning. Bitcoin decides the quarter tonight. 3 Stocks at a Major Turning PointSomething unusual is happening beneath the surface of three widely followed stocks.
In each case, the fundamentals are saying one thing... while institutional activity, management signals or the options market are saying something else. That kind of disagreement can matter. Because when the evidence stops lining up, the next move in the story often comes down to a handful of signals most investors never think to watch. Our new FREE Market Tell Special Report breaks down three of these situations, and shows you exactly what we’re watching next. Get the Free Report: 3 Stocks at a Major Turning Point → |
|